Benefits Realisation Management: A Register, an Owner, a ₹ Example
Benefits realisation management is the practice of naming each benefit a project promises, measuring it against a baseline, and giving one owner the job of delivering it after the project closes.
By Sanjeev Kumar, Founder · Updated 4 Oct 2026
Key takeaways
- Benefits realisation management means each promised benefit has a measure, a baseline, a target date and one named owner who can change the process that produces it.
- An output is what the project hands over, an outcome is what changes in how people work, and a benefit is the measurable value that results. Only the benefit belongs in the business case.
- Adoption speed moves payback more than most business cases admit. In our model, the same project pays back at about month 18, 22 or 28 depending on adoption.
- The project manager should not own benefits. Hand the register to a business owner at closure, with review dates after go-live.
In this article
- 1What is benefits realisation management, and how is a benefit different from an output?
- 2What does a benefits register row look like?
- 3How does slow adoption change when a project pays back?
- 4Who owns a benefit after the project manager leaves?
- 5How do you test a benefit statement before putting it in a business case?
- 6When should benefits be reviewed after the project closes?
- 7Which Augment Consultancy course covers BRM and benefits planning?
- 8Frequently asked questions
A project can finish on time, on budget and to scope, and still leave the organisation where it started. Delivery is a fact about the project. A benefit is a fact about the business, and it usually appears months after the project team has moved on.
The sums involved are large. The UK government's 189-project major projects portfolio expects £603.6 billion of benefits expressed in money, according to the Major Projects Annual Report 2025-26 from the National Infrastructure and Service Transformation Authority (NISTA), published on 13 July 2026. Expected benefits are a forecast. Someone has to turn them into results.
This page gives you three things to close that gap: a one-row benefits register you can copy, a four-part test for any benefit statement, and a worked example in rupees. The example shows how slow adoption pushes back the month in which the project pays for itself. It also answers the question that stalls most teams: who owns a benefit once the project manager has left.
What is benefits realisation management, and how is a benefit different from an output?
Benefits realisation management (BRM) is the set of practices that identify benefits, tie them to strategy, make sure they are realised as delivery progresses, and keep them sustained after delivery ends. PMI's Benefits Realization Management Framework organises this as three stages: Identify, Execute and Sustain.
The confusion that catches most people is the difference between three levels:
| Level | What it is | Example (invoice automation) |
|---|---|---|
| Output | What the project delivers | An automated invoice-approval system |
| Outcome | What changes in how work is done | Approvers clear invoices in the system, not by email |
| Benefit | The measurable value that follows | Cost to process one invoice falls from ₹180 to ₹95 |
A benefit can be tangible, such as money saved or student numbers gained, or intangible, such as reputation or capacity for change, as Oxford Brookes University's project toolkit puts it. A quick test: if the sentence only says something was delivered (a system is live, staff are trained), it is an output. A benefit is a measurable change in the business that would not have happened without the project.
What does a benefits register row look like?
A benefits register row holds nine fields, one row per benefit. The first seven draw on the benefits register content described in the Teal Book, the UK government's Government Project Delivery guidance (chapter 19, last modified 1 July 2026), and on the plan elements in PMI's framework. Review dates and status are our additions, because a register that is never reviewed is a document, not a control.
| Field | What to enter | Example row |
|---|---|---|
| Benefit statement | Verb, measure, from, to, by when | Reduce cost to process a supplier invoice from ₹180 to ₹95 by month 12 after go-live |
| Category | Financial or non-financial; tangible or intangible | Financial, tangible |
| Measure | The formula and its data source | Accounts payable operating cost ÷ invoices processed, from the finance ledger |
| Baseline | Current level, date, source | ₹180, average of the three months before go-live |
| Target and date | The level and the day it must be reached | ₹95 by month 12 |
| Benefit owner | One named person with decision rights | Head of Accounts Payable |
| Dependencies and assumptions | What must be true | All suppliers onboarded; approvers trained; manual route switched off |
| Review dates | Dates, including after closure | Months 3, 6, 12 after go-live |
| Status | On track, at risk, realised, dropped | At risk |
The Teal Book also advises against giving one owner too many benefits. Keep rows to a number the owner can actually watch.
How does slow adoption change when a project pays back?
Slow adoption delays payback by months even when the project is delivered perfectly. Here is our worked model, built on the example row above. The inputs are our assumptions for illustration, not data from a real project.
- Volume: 12,000 invoices a month.
- Saving: ₹180 − ₹95 = ₹85 per invoice, so ₹85 × 12,000 = ₹10.2 lakh a month at full adoption, or ₹1.224 crore a year.
- Project cost: ₹1.8 crore (₹180 lakh).
- Adoption after go-live: 30% in months 1 to 3, 60% in months 4 to 6, 90% in months 7 to 12.
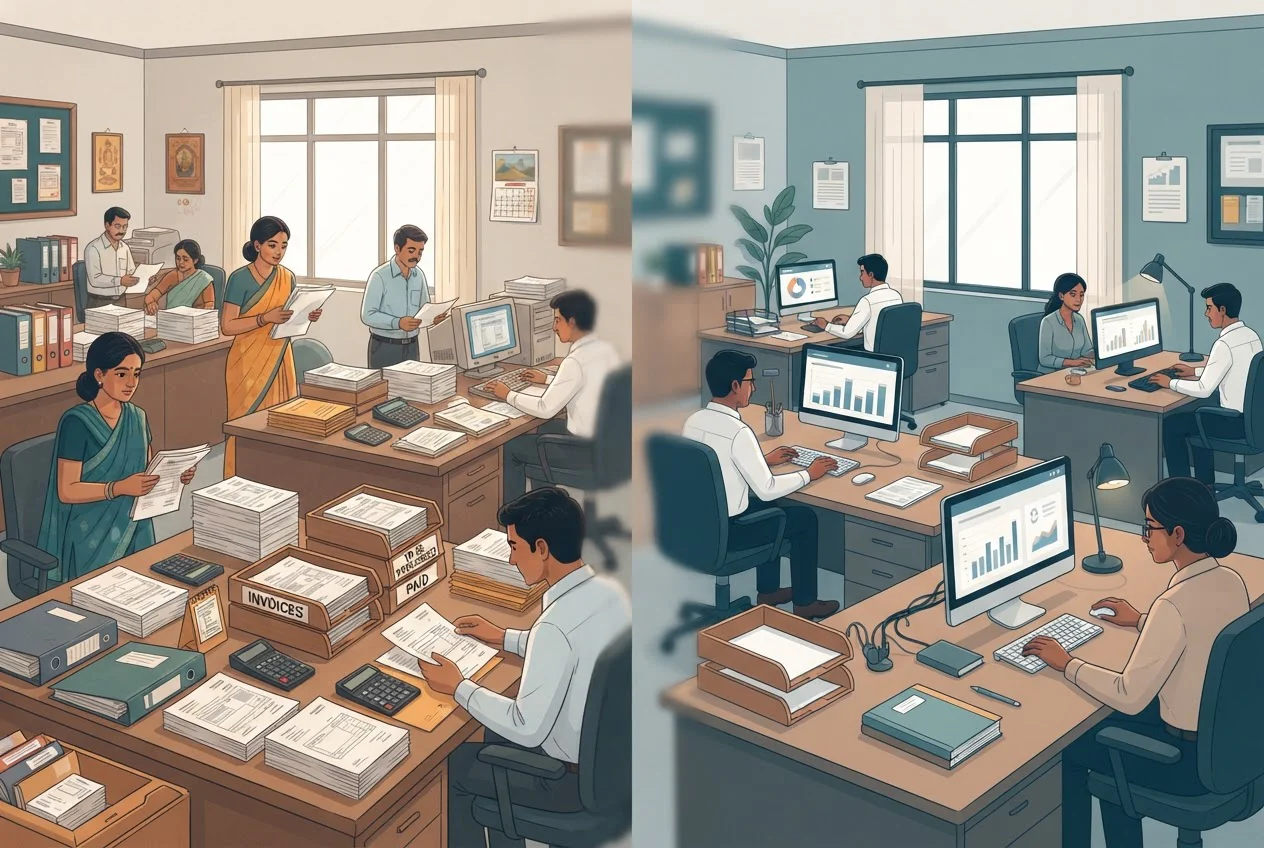
The business case assumes 100% from day one, so payback is 180 ÷ 10.2 = 17.6 months. With the ramp, the first year delivers ₹10.2 lakh × (3 × 0.3 + 3 × 0.6 + 6 × 0.9) = ₹10.2 lakh × 8.1 = ₹82.62 lakh. That leaves ₹97.38 lakh still to recover.
| Scenario from month 13 | Monthly benefit | Months to recover ₹97.38 lakh | Payback |
|---|---|---|---|
| Business case: 100% from go-live | ₹10.2 lakh | n/a (17.6 months in total) | About month 18 |
| Adoption reaches 100% | ₹10.2 lakh | 9.5 | About month 22 |
| Adoption stays at 90% | ₹9.18 lakh | 10.6 | About month 23 |
| Adoption falls back to 60% once the project team leaves | ₹6.12 lakh | 15.9 | About month 28 |
A delivery report would read green in all four rows, because the project was delivered in each. Four of the ten months between the first and last row come from the first-year adoption ramp. The other six come from adoption falling back to 60% once the project team leaves. That second gap is an ownership problem, which the next section addresses. Treat adoption as a risk that the benefit owner reports on at every review.
Who owns a benefit after the project manager leaves?
A named business leader who can change the process that produces the benefit owns it, not the project manager. The Association for Project Management (APM) notes that benefits typically arrive after handover, so the sponsor, not the project manager, stays accountable. The Teal Book defines the benefit owner as the named individual who confirms the benefit, agrees the plan and reports on realisation.
In PMI's 2016 research, naming an accountable owner was far more common in mature organisations. That is an association, not proof of cause, and the data are a decade old. PMI surveyed 774 managers accountable for benefits on projects of US$250,000 or more. In its ownership and accountability study, 94% of high-maturity organisations always formally named who is accountable for benefits, against 19% of low-maturity ones. High maturity meant a score of 60 or more out of 64 on a 16-item practice scale, and low meant under 46. In the same year, PMI's Pulse of the Profession 2016 reported that only 17% of organisations had high benefits realisation maturity, unchanged for three years, and nearly four in ten had low maturity.
Our recommendation for common situations:
| Situation | Who holds the benefit | Why |
|---|---|---|
| Benefit arises inside one department | Head of that department | They control staffing and process rules |
| Benefit spans departments | Split into parts, one owner per part; the sponsor holds the total | One person per number avoids shared blame |
| Sponsor leaves mid-programme | Reassign at the next governance meeting, with the register | An owner who never agreed to a target will not chase it |
| Nobody senior will accept the benefit | Mark it unowned and remove it from the business case | An unowned benefit is a hope |
| Project closes | Project manager hands over the register and the measurement routine | Handover is the last delivery task |
How do you test a benefit statement before putting it in a business case?
Run four tests on each statement before it enters the register. Each has a clear pass or fail.
- Number testThe statement contains a measure, a baseline, a target and a date. Fail if any of the four is missing, including "improve" or "streamline" with no figure.
- Owner testOne named person can change the process behind the number without asking the project for permission. Fail if the only name is the project manager or "the business".
- Output testDelete the system or deliverable's name from the sentence. Pass if it still describes a change in the organisation. Fail if it only describes something delivered.
- Closure testAt least one review is dated after the project closes, with a named person who reports it. Fail if every review date falls before closure.
A benefit that fails the number or owner test is not ready for approval. Fixing it takes a conversation, not a document.
When should benefits be reviewed after the project closes?
Review each benefit at 3, 6 and 12 months after go-live, plus once on the target date if it falls later. Add at least one review dated after the project closes, with a named person reporting it. This is our recommendation for benefits that depend on people changing how they work. The Teal Book places reviews before closure and again afterwards, through further assurance reviews and formal post-implementation reviews. PMI's framework adds a sustainment plan covering the risks, measures and tools needed to keep benefits flowing.
The early reviews check adoption, the cause of most delay in the model above. The last one checks the number. Record what was measured, by whom, against which baseline, so the figure survives a change of owner.
Which Augment Consultancy course covers BRM and benefits planning?
Module 6 of our Program Management Essentials course, "Benefits Planning & Value Realization", covers benefit identification, categorisation, benefit management, transition and sustainment. It is part of the 12-week course, which includes real-world templates and case studies.
If you are preparing a PgMP® (Program Management Professional) or PfMP® (Portfolio Management Professional) application, a benefits realisation plan, baseline or target is the kind of evidence that shows you protected organisational results. Our PgMP application terminology guide covers how to word it.
Program Management Essentials runs over 12 weeks and costs US$99 as of October 2026.
Frequently asked questions
Return on investment (ROI) is one financial measure of a benefit. Benefits realisation management covers the wider job of identifying, owning and sustaining every benefit, financial and non-financial. PMI's Pulse of the Profession 2016 describes it as the means of determining ROI and of identifying intangible benefits such as customer satisfaction.
A benefits breakdown structure is a map from a strategic goal back through the business change, new capability and project output that must happen for the benefit to arrive. It shows which dependencies each benefit rests on. Our portfolio strategic alignment framework covers the link from strategy to investment.
Sources
- 1.NISTA, Major Projects Annual Report 2025-26 (13 July 2026)
- 2.PMI, Benefits Realization Management Framework (2016)
- 3.PMI, Establishing benefits ownership and accountability (2016)
- 4.PMI, Pulse of the Profession 2016
- 5.UK Government Project Delivery, Teal Book chapter 19: Benefits management
- 6.APM, What is benefits management and project success?
- 7.Oxford Brookes University, Benefits realisation toolkit
- 8.Worked example: our own model, with the assumptions and arithmetic shown in the page